
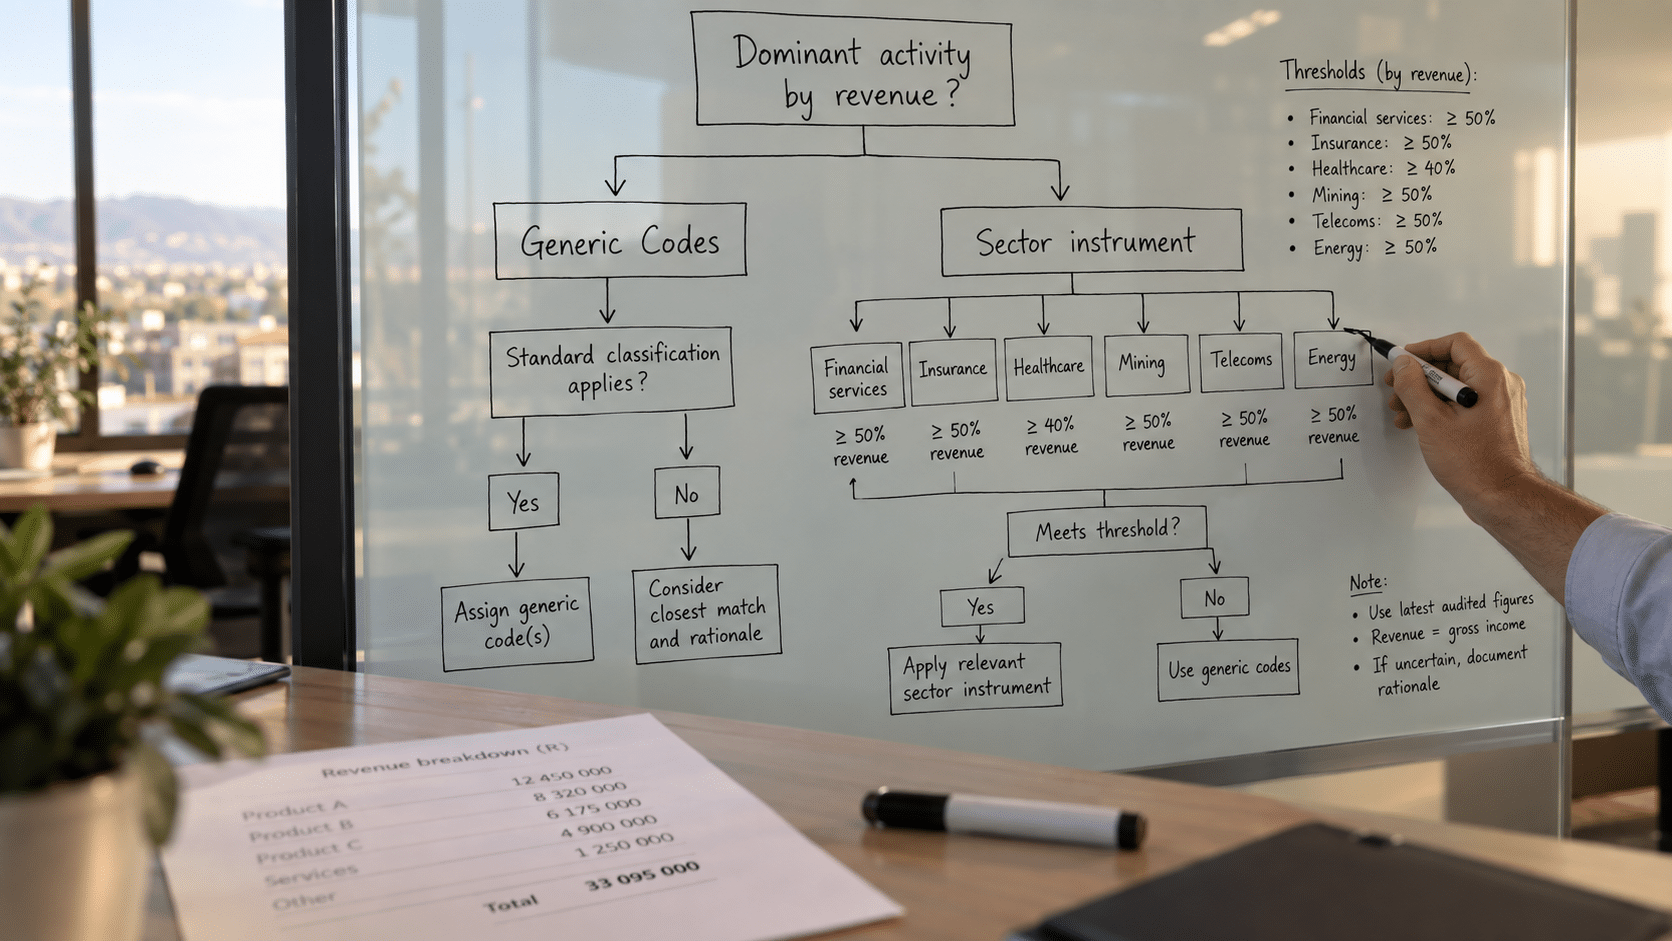
A B-BBEE code comparison is not really a choice, and that is the first thing most corporates get wrong. You do not pick which framework measures your business. Your dominant revenue activity picks it for you, and getting that determination wrong is the single most expensive error in this whole area of compliance.
Two frameworks exist. The generic Codes of Good Practice govern most of the economy. Ten industries have their own gazetted instrument that overrides the generic one for businesses inside them. Which set applies is a question of fact, decided by what you do, not a preference you exercise. The full list of gazetted industries sits in the B-BBEE sector codes guide.
Where it gets commercially serious is the gap between the two. Sector instruments frequently set harder targets, different thresholds and extra elements. A business measured against the wrong one can spend two years building the wrong scorecard.
Quick Answer
A B-BBEE code comparison comes down to one question: does a gazetted sector instrument apply to your dominant activity? If yes, it overrides the generic Codes entirely and you are measured against its targets, which are often harder — higher ownership, lower exemption thresholds, or an extra element. If no gazetted instrument covers your industry, the generic Codes apply directly. The determination is made on your main revenue source, confirmed by your verification agency, and it decides every number on your scorecard.
Not certain which framework governs your business? Send us your revenue mix and we will make the determination in writing →
How the B-BBEE Code Comparison Actually Works
The rule sounds simple and trips people constantly: a gazetted sector instrument, where one exists for your industry, replaces the generic Codes for businesses whose dominant activity falls inside it. It does not supplement them. It replaces them.
That means a construction firm is not measured on the generic scorecard with some construction flavouring. It is measured on the construction instrument, full stop, with that instrument’s targets, thresholds and elements. The generic Codes become irrelevant to it except where the instrument borrows from them.
Dominant activity is the deciding test, and it is measured by revenue. A group that manufactures and also transports its goods is placed by where the majority of its turnover sits, not by which activity feels more central to its identity.
Why the determination is not always obvious
Modern businesses rarely do one thing. A company might grow produce, pack it, and run a logistics arm, touching agriculture, an unregulated activity, and transport all at once. Each of those points at a different framework.
The revenue test resolves it, but only if someone actually runs it. Where nobody does, the business defaults to whatever it assumed at the first verification and often carries that assumption, right or wrong, for years.
The determination is a fact, not a choice
You cannot elect the generic Codes because they look easier, nor a sector instrument because it looks prestigious. The applicable framework follows your dominant revenue activity as a matter of law. The only real decision is whether to restructure the business so that a different activity becomes dominant, which is a commercial decision with a compliance consequence, not the other way round.
Where the Two Frameworks Genuinely Differ
If the frameworks were identical, none of this would matter. They are not, and the differences cluster in four places.
Thresholds. The generic exemption ceiling is R10 million. Several sector instruments moved it. Tourism dropped it to R5 million, catching businesses that would be exempt anywhere else. The still-unaligned transport instrument sits on the old R5 million and R35 million bands entirely.
Ownership targets. The generic benchmark is 25%. Property lifts it to 27% for asset-owning entities. Agriculture sets 30% of productive land. Forestry keeps 25% but pays bonus points toward 30%. Renewable-energy procurement, though not a gazetted instrument, contractually demands far more.
Extra elements. Property carries a sixth element, economic development, that has no generic equivalent. Businesses using a generic template simply have no line for it and score zero.
Priority-element rules. The generic priority set is ownership, skills, and enterprise and supplier development. The property instrument makes management control a priority instead. The transport instrument has no priority elements at all.
A Side-by-Side on the Points That Move Money
The table below is a decision aid, not a full scorecard. It shows where a business measured under the wrong framework would misprice its obligation most badly.
| Measure | Generic Codes | Where a sector instrument departs |
|---|---|---|
| Exemption ceiling | R10 million | Tourism R5m; transport R5m |
| Small-enterprise ceiling | R50 million | Tourism R45m; transport R35m |
| Black ownership target | 25% | Property 27%; agriculture 30% of land |
| Number of elements | Five | Property six (adds economic development) |
| Priority elements | Ownership, skills, ESD | Property swaps in management control; transport has none |
| Affidavit route for small entities | Available | Transport instrument: not available |
One pattern holds almost everywhere: the sector instrument is harder, not easier. The instinct to hope a sector instrument applies because it sounds tailored is usually the wrong instinct financially.
The 2026 Amendment Angle Nobody Weighs
There is a dimension to this that most advisers miss entirely, and in 2026 it is the most important one.
The generic framework and the sector instruments do not change on the same clock. Draft amendments to the generic Codes were gazetted in January 2026 with a comment period that has since closed. Those amendments apply to the generic framework directly and immediately on their effective date.
The ten gazetted industries are insulated. Their instruments continue on existing terms until each is separately amended and re-gazetted, a process that historically takes years. One instrument, transport, has been waiting for alignment since 2016 and still runs on its 2009 form.
So the framework you fall under decides not only your current targets but your exposure to change. A generic-Codes business absorbs the 2026 amendments first. A sector-instrument business gets a buffer measured in years. That is a real difference in planning certainty, and it belongs in any serious weighing-up of the two.
The framework decides your exposure to reform, not just your targets
In 2026 this is the sharpest practical difference between the two. Generic-Codes industries — retail, energy, manufacturing, professional services — feel amendments as soon as they take effect. The ten gazetted-instrument industries are shielded until their own instrument is separately updated. When you weigh the two, weigh the stability, not only the numbers.
How to Run the Determination Properly
The process is not complicated, but each step has to actually happen rather than being assumed.
Establish dominant revenue activity. Break turnover down by activity and identify where the majority genuinely sits. For a diversified group this may need doing per legal entity, because each measured entity stands on its own.
Check the gazetted list against that activity. If a sector instrument covers the dominant activity, it governs. If none does, the generic Codes apply. This is a factual lookup, not a judgement call.
Confirm the boundary cases in writing. Where the activity sits near the edge of a sector definition, the verification agency should confirm the determination before any scorecard work begins. A written determination settles later disputes with clients and auditors instantly.
Model the consequence. Once the framework is fixed, model the targets that actually apply. This is where a business discovers whether its assumed position was optimistic, and where there is still time to act if it was.
Understanding the mechanics of how recognition levels work matters here, but the determination comes first. Every level calculation downstream depends on getting the framework right.
When Restructuring the Business Changes the Answer
Because the framework follows dominant activity, a business can in principle change which framework applies by changing what it mostly does, or how its activities are split across legal entities. This is legitimate, but it is a commercial decision first and a compliance one second.
Consider a group that manufactures and distributes. If manufacturing is dominant, an unregulated activity governs and the generic Codes apply. If distribution grows until transport becomes dominant, the group can find itself pulled under the still-unaligned transport instrument, with its lower thresholds and its missing affidavit route. The same growth that looked like commercial progress quietly changed the compliance regime.
The reverse can be engineered deliberately. Splitting a diversified business into separate entities lets each be measured under the framework that fits its own dominant activity, rather than the whole group answering to whichever single activity happens to be largest. For some groups this materially improves the achievable position.
None of this should ever be done for the compliance outcome alone. Restructuring carries tax, financing and operational consequences that dwarf the scorecard. But when a restructuring is already being contemplated for commercial reasons, the framework consequence belongs in the analysis rather than being discovered afterwards.
The group-scorecard trap
Diversified groups make one error repeatedly: they build a single group scorecard and assume one framework covers everything. In reality each measured entity stands alone, and a group can legitimately contain entities measured under three different instruments at once.
Averaging them into one position is not a simplification. It is a misstatement, and it is the kind of thing that unravels when a large customer runs its own due diligence on a supplier’s certificate and finds the underlying entity was measured against the wrong targets.
Reading the Comparison the Right Way Round
The most useful mental model is to stop thinking of this as a contest between two frameworks and start thinking of it as a placement exercise. The business is placed by fact. The only questions worth energy are whether the placement has been confirmed, and whether the commercial structure that drives it is the one you actually want.
A business that has confirmed its framework in writing, modelled the correct targets, and consciously chosen its activity mix has done everything this comparison can offer. A business still assuming its position from a determination nobody documented is carrying a risk it cannot see, and the risk compounds every cycle it goes unchecked.
Never had your framework confirmed in writing? That is the first thing to fix, and we can settle it quickly →
What Changes When the Framework Is Confirmed First
The figures below come from a composite of diversified-group mandates across Gauteng and the Western Cape.
| Position | Before determination | After correct determination |
|---|---|---|
| Framework applied | Generic, assumed | Sector instrument, confirmed in writing |
| Recognition level | Level 6, built on wrong targets | Level 3 on the correct scorecard |
| Ownership target modelled against | 25% | Correct sector target confirmed |
| Sixth element | Not measured, scored zero | Identified and claimed where applicable |
| Wasted scorecard effort | Two verification cycles | Redirected to the correct elements |
| Client and tender disputes | Framework queried repeatedly | Settled by written determination |
The wasted-effort line is the quiet cost. A business measured against the wrong framework does not fail loudly. It simply spends money improving numbers that were never the ones being scored.
Who This Is NOT For
Single-activity businesses well inside one definition. If you run one clear activity that plainly sits in a named industry, your framework is not in doubt and you do not need a determination exercise. Proceed straight to the scorecard.
Exempt micro enterprises on an affidavit. Below the exemption ceiling, the framework distinction rarely changes your outcome. An affidavit is the whole obligation, except under the transport instrument, which has no affidavit route.
Anyone hoping to pick the easier framework. The determination is a matter of fact. If the intention is to elect the softer of the two, that option does not exist, and pursuing it wastes everyone’s time.
Businesses wanting a number this week. A correct determination and a modelled scorecard take time. If a tender closes in days, an accredited agency working from your existing position will serve you faster than a strategic review.
Who this does suit: diversified groups spanning more than one industry definition, businesses near the boundary of a sector definition, and any corporate that has never confirmed in writing which framework its verification agency actually applies.
The Insignis View on the B-BBEE Code Comparison
We treat the determination as the first deliverable, not a preliminary. Before any scorecard modelling, we establish dominant activity by revenue, check it against the gazetted list, and get the verification agency to confirm the framework in writing. Almost every expensive mistake we are called in to fix traces back to this step being skipped.
For diversified groups the work goes further, because each measured entity can fall under a different framework. A holding company, a manufacturing subsidiary and a distribution arm may answer to three different instruments, and the group scorecard has to reflect that rather than average it away.
The determination is also a tax and structuring question, which is where a chartered accountant reads it differently. Whether to let an activity remain dominant, or restructure so another takes over, has consequences well beyond the scorecard. Our B-BBEE consulting scope runs the whole assessment from our Centurion base.
The authoritative list of which instruments are gazetted, and therefore which industries are governed by a sector framework, is maintained by the regulator. The dtic register of Codes and sector instruments is the reference point for any determination.
Running a group with several activities under one roof? Have each entity’s framework determined before your next verification →
Frequently Asked Questions
Can a business choose between the generic and sector frameworks?
No. The applicable framework is decided by the business’s dominant revenue activity as a matter of fact. Where a gazetted sector instrument covers that activity, it applies and overrides the generic Codes. Where none does, the generic Codes apply. It is a determination, not an election.
What decides which framework applies?
Dominant activity, measured by revenue. A business is placed by where the majority of its turnover sits, not by which activity it considers central. For diversified groups, the test is applied to each separate measured entity.
Are sector frameworks always harder than the generic Codes?
Usually, though not universally. Sector instruments frequently set higher ownership targets, lower exemption thresholds, or additional elements. Some also add concessions. The only way to know the net effect is to model the specific instrument against the business.
Which industries have their own sector instrument?
Ten gazetted industries, including financial services, tourism, property, construction, agriculture, forestry, transport, information technology, marketing and mining. Industries without a gazetted instrument, such as retail and energy, fall under the generic Codes.
How do the 2026 amendments change the comparison?
They apply to the generic framework directly, so generic-Codes businesses feel them first. The ten gazetted industries are insulated until their own instrument is separately amended, giving them a buffer that generic-Codes industries do not have.
What happens if the wrong framework is applied?
The business builds a scorecard against targets it is not measured on, typically discovering the error at a verification or a lost tender two cycles later. The correct determination is quick and cheap by comparison, and settles client and auditor disputes in writing.
Get the framework determination in writing first
A determination review establishes your dominant activity by revenue, confirms whether a sector instrument or the generic Codes govern each measured entity, and gets that position agreed with your verification agency before any scorecard work begins. You start the correct scorecard from day one.
No obligation. We will get back to you within 24 hours.
Request a framework determination
Dr. Este Welman, CA(SA)
Founding Partner, Insignis Solutions
Dr. Welman is a Chartered Accountant holding a PhD in Economic Transformation from the Da Vinci Institute, an M.Comm in Tax from North-West University, and a B-BBEE Management Diploma from Wits. She is a member of SAICA. Diversified groups bring her the determination problem in its hardest form: several subsidiaries, several dominant activities, and a group scorecard that has to respect which framework governs each one rather than smoothing them into a single wrong answer.