
B-BBEE retail south africa compliance has no industry-specific rulebook, and that answer surprises most merchants who go looking for one.
Ten industries hold their own gazetted instrument. Stores, chains and wholesalers are not among them, which means the generic Codes of Good Practice apply directly and without modification.
That absence is not a gap in the law — it is the position, and it has a consequence in 2026 that the ten gazetted industries do not face. If you want to see which industries do hold their own instrument, the B-BBEE sector codes guide sets out the full list.
The consequence is this. When the generic framework is amended, merchants feel it immediately. Businesses inside a gazetted industry do not, because their instrument only changes when it is separately aligned.
Quick Answer
B-BBEE retail south africa compliance is measured under the generic Codes of Good Practice, because no gazetted instrument exists for this industry. Standard thresholds apply: exemption below R10 million, qualifying small enterprise to R50 million, large enterprise above that. Three priority elements carry 40% sub-minimums and a one-level discount. Critically, the draft amendments gazetted in January 2026 apply to the generic framework directly, so merchants are exposed to them ahead of the ten gazetted industries.
Trading across stores, wholesale and online? Let us confirm your measured entity structure before verification →
What B-BBEE Retail South Africa Compliance Requires
Start with what does not apply, because that saves a wasted search. There is no merchant-specific instrument, no dedicated charter council, and no bespoke scorecard. The regulator’s own register lists gazetted instruments for financial services, forestry, property, tourism, construction, information technology, marketing, agriculture, transport and mining. Stores are absent from that list.
So the generic framework governs, with the standard bands and the standard five elements.
| Category | Threshold | What is required |
|---|---|---|
| Exempt micro enterprise | Below R10 million | Sworn affidavit, deemed Level 4 |
| Qualifying small enterprise | R10m to R50 million | Scorecard verification, or affidavit if 51% black owned |
| Large enterprise | Above R50 million | Full five-element scorecard |
| Priority elements | Three | Ownership, skills, enterprise and supplier development |
| Sub-minimum on each | 40% of target | Miss one and the level drops by one |
| Wholly black-owned small entity | Level 1 at 135% | Affidavit route, no verification needed |
Nothing there is unusual. What is unusual is how those standard rules interact with how a merchant business is actually built.
Where the Generic Scorecard Meets a Store Network
Four structural features of this industry change the scoring picture, and none of them are addressed by any guidance written for a generic corporate.
Procurement is the dominant lever, by a wide margin. A merchant’s cost base is overwhelmingly bought-in goods. That makes preferential procurement the largest available points pool by some distance, and the one where a percentage-point shift moves the total more than anything else on the scorecard.
Franchise structures split the measured entity. A franchisor and each franchisee are separate measured entities with separate revenue and separate obligations. A franchisee below R10 million is exempt on an affidavit while the franchisor above R50 million carries a full scorecard, and neither inherits the other’s rating. Group-level assumptions here are consistently wrong.
The workforce is young, casual and high-turnover. That is a genuine difficulty for management control and employment equity, and a genuine opportunity for skills development and youth employment. Most operators experience only the difficulty.
Imported stock shrinks the scoreable base. Goods bought offshore cannot carry a local supplier rating. A business with heavy import content has a smaller pool of procurement spend available to score against, which changes what a realistic target looks like.
Franchise groups are not measured as groups
Each franchisee is its own measured entity with its own turnover band, its own obligation and its own certificate. A franchisor cannot extend its rating downward, and a franchisee cannot rely on the brand’s certificate when a corporate customer or a landlord asks. Where a group has fifty franchisees, it has fifty separate positions to manage, and most of them sit below the exemption line on an affidavit.
The Youth Employment Route Most Merchants Overlook
This industry employs more young people than almost any other, and there is a mechanism built precisely for that.
The Youth Employment Service allows a measured entity that meets defined youth employment targets to be recognised with a level improvement. The regulator publishes both the enabling gazette and a practice note explaining how it operates.
The fit with a store network is close to ideal. Merchants already recruit young, already run structured onboarding, and already carry the seasonal headcount that the mechanism is designed to reward. Businesses in industries with older, more specialised workforces cannot use it nearly as easily.
What stops most operators is not eligibility. It is that the youth intake is managed as an operational staffing matter and never connected to the compliance calendar, so the recognition is simply never claimed.
Hiring seasonal youth staff every year? Ask whether your intake already qualifies for level recognition →
Why B-BBEE Retail South Africa Exposure to the 2026 Amendments Is Immediate
This is the point that should reach a board, and it is the one genuine advantage of understanding that no bespoke instrument exists here.
Draft amendments to the generic framework were gazetted in January 2026 under Gazette 54032, with a sixty-day comment period that closed at the end of March. They include a proposed Transformation Fund and revised procurement targets. Those amendments apply to the generic Codes.
Businesses inside the ten gazetted industries are insulated for now. Their instrument continues on its existing terms until it is separately amended and re-gazetted, a process that historically takes years and in one case has never been completed at all.
Merchants have no such buffer. Whatever is finalised for the generic framework lands on this industry on the effective date, without an alignment process in between.
What that means for planning
It argues for building ahead rather than waiting for certainty. Procurement is the element most likely to be affected and the slowest to move, because it depends on supplier relationships rather than an internal decision.
A supplier base rebuilt toward higher-rated and black-owned suppliers takes eighteen months to shift meaningfully. A supplier base rebuilt after an amendment takes effect is a business trading at a discounted level in the interim. The scorecard improvement guide sets out the wider sequencing.
Building the Supplier Register Properly
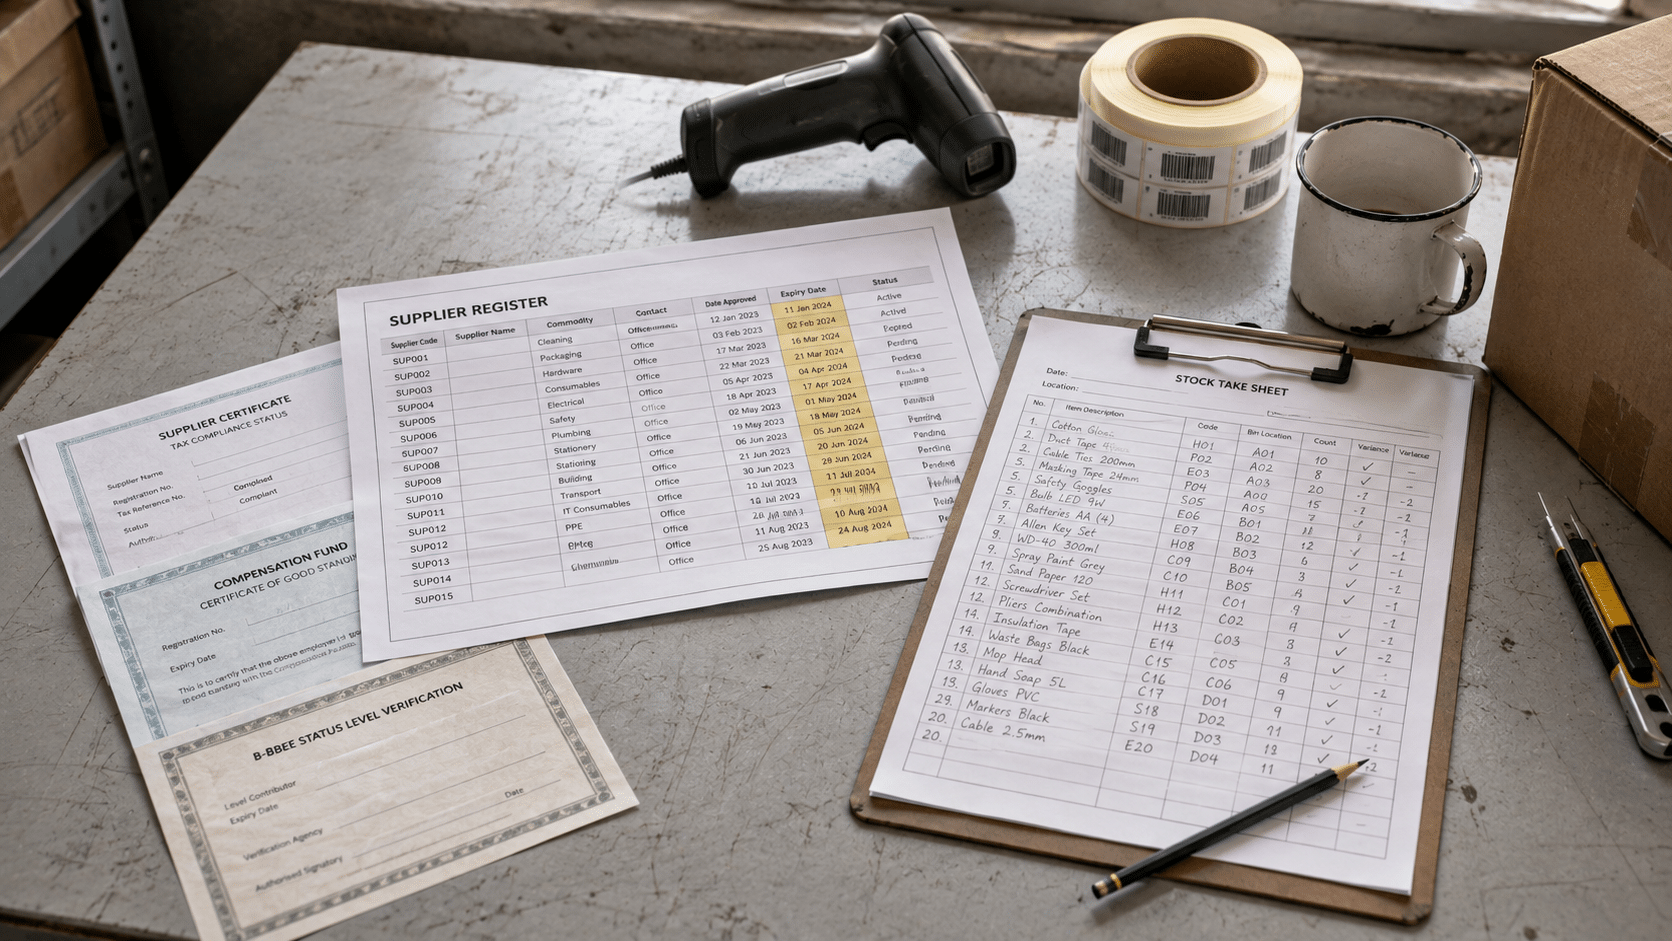
Since procurement carries the most weight here, the register deserves more than a passing mention. Most that we inherit are spreadsheets built once for a verification and never touched again.
A register that actually works holds four things against every supplier: the entity name as it appears on the certificate, the certificate’s recognition level, its expiry date, and the spend recorded against that supplier in the measurement year. Miss the expiry date and the whole exercise degrades quietly, because a certificate that lapsed in month three scores nothing for the spend in month four.
The renewal diary is what separates a register from a snapshot. Certificates expire on a rolling basis across hundreds of suppliers, and chasing them in the final quarter recovers nothing for spend already incurred.
Ownership of the register also matters. Left with the finance team it becomes a year-end scramble; left with the buying team it stays current, because buyers are already in contact with these suppliers every month.
Where the quick wins usually sit
Two categories reliably produce points that were always available.
Small and black-owned suppliers already in the base are the first. Merchants buy locally from cleaning contractors, packaging suppliers, maintenance firms and transport operators, many of which qualify for enhanced recognition. Their affidavits are simple to collect and frequently worth more per rand than a large supplier’s certificate.
The second is spend currently routed through intermediaries. Where a buying group or agent sits between the merchant and the underlying supplier, the recognition attaches to the intermediary. Establishing whether the arrangement can be evidenced through to the underlying supplier sometimes releases a substantial block of spend.
Managing a Multi-Entity Group
Groups in this industry rarely consist of one company, and the compliance consequences of that are routinely underestimated.
A typical structure carries a property-holding company, an operating company per region or banner, a central buying entity and sometimes a separate online business. Each is measured on its own revenue, and the central buying entity is frequently the one carrying the procurement spend that the operating companies would like to claim.
That last point causes real difficulty. If buying sits in a shared services entity, the procurement points sit there too, and the trading entities that face customers may score poorly on the element that matters most to them.
There is no trick that solves this, but there is a decision. Either the group accepts the split and manages each entity’s position separately, or it restructures how buying is contracted so that spend is recognised where the certificate is needed. Both are legitimate. Choosing neither, which is the common outcome, produces a group whose customer-facing entities certificate worse than the business deserves.
Why Ratings Fail at Verification in This Industry
Four causes recur, and each one is a records or structure problem rather than a strategic one.
Supplier certificates are never collected at scale. A merchant may deal with hundreds of suppliers. Without a maintained register linking each to a current certificate, spend that would have scored records against unrated suppliers by default.
Store-level training is invisible. Till operation, stock handling, food safety and customer service training is delivered continuously across a network. Attendance and completion evidence is rarely captured centrally in the form an agency requires.
Franchise boundaries are assumed. A group presents a consolidated position that does not match the legal structure, and the agency measures the entity rather than the brand.
Casual staff sit outside the workforce data. Seasonal headcount often lives in a separate payroll or agency arrangement and never reaches the employment equity submission, understating the very demographics that would have scored.
What Changes When the Structure Is Mapped First
The figures below come from a composite of chain and franchise mandates across Gauteng and the Western Cape.
| Position | Before engagement | After 18 months |
|---|---|---|
| Recognition level | Level 5, discounted from Level 4 | Level 2, no discount applied |
| Supplier register | None maintained | 412 suppliers mapped to current certificates |
| Procurement spend traced | R31 million | R186 million traced and claimed |
| Store-level training claimed | R0 of R1.4 million delivered | R1.2 million evidenced and claimed |
| Youth employment recognition | Not claimed | Claimed, contributing to the level |
| Measured entities identified | One, assumed | Four, each separately positioned |
The procurement line carries almost all of the movement, and none of it came from changing suppliers. The business was already buying from rated suppliers at scale. It had simply never built the register that connects the spend to the certificates.
The register is the whole exercise
For a merchant, the single highest-return compliance investment is a maintained supplier register with current certificates attached and a renewal diary against each one. It requires no change to buying decisions, no new spending and no negotiation. It converts procurement you are already committed to into the largest points pool available to you.
Who This Is NOT For
Independent stores below R10 million. A sworn affidavit is the entire obligation and costs nothing to obtain. Nobody may charge you for one. Advisory work at this size belongs in stock, not compliance.
Franchisees waiting for the brand to solve it. Your rating is yours, and no franchisor certificate covers it. What you need is usually an affidavit rather than an adviser, so start there before spending anything.
Businesses trading almost entirely on imported stock. With a thin local procurement base, the largest lever in this industry is mostly unavailable, and the achievable ceiling is correspondingly lower. Worth knowing before commissioning a strategy.
Anyone seeking a rating before a specific tender next month. A verification takes time and the priority sub-minimums cannot be closed in weeks. An accredited agency can tell you what is achievable in the window better than we can.
Who this does suit: chains, wholesalers, franchisors and multi-store groups above R50 million, particularly those supplying corporate or state customers, and those whose procurement spend has never been mapped against a supplier register.
What Insignis Prioritises in B-BBEE Retail South Africa Work
We start with the legal structure rather than the brand. Establishing how many measured entities actually exist, and which band each falls into, decides everything downstream — and in a franchise network the answer is almost never the one the group assumes.
The second priority is the supplier register, because in this industry procurement is where the points are. We build it once properly, with a renewal diary attached, and hand it over as an operating asset rather than a report.
The practice is led by a Chartered Accountant who holds a doctorate in Economic Transformation from the Da Vinci Institute and an M.Comm in Tax. In a thin-margin business, the cost of a compliance decision has to be modelled against the margin it protects, and that is an accounting judgement as much as a transformation one.
Engagements run out of our Centurion office; the consulting scope sets out where we pick the work up and where we hand it back.
Because the generic framework governs here, the regulator’s own materials are directly usable rather than needing translation through an industry instrument. The dtic page for the Codes of Good Practice carries the gazetted Codes, the affidavit templates and the youth employment practice note in one place.
Supplier spend never mapped to certificates? Start with a procurement register review →
Frequently Asked Questions
Is there a B-BBEE sector code for retail?
No. No gazetted instrument exists for this industry, so the generic Codes of Good Practice apply directly. Ten industries hold their own gazetted codes, including financial services, tourism, property, construction and agriculture, but stores and wholesalers are not among them.
What thresholds apply to a retail business?
The standard generic bands: exemption below R10 million in annual turnover, qualifying small enterprise between R10 million and R50 million, and large enterprise above R50 million. Exempt entities need only a sworn affidavit and are deemed Level 4 contributors.
Are franchisees measured separately from the franchisor?
Yes. Each is a separate measured entity with its own turnover band, obligation and certificate. A franchisor’s rating does not extend to franchisees, and a franchisee cannot rely on the brand’s certificate when a customer or landlord requests one.
How do the 2026 amendments affect retail businesses?
Directly and without delay. The draft amendments gazetted in January 2026 apply to the generic framework, which governs this industry. Businesses in the ten gazetted industries are insulated until their own instrument is separately amended, but merchants have no equivalent buffer.
Which element offers the biggest gain?
Preferential procurement, by a wide margin. A merchant’s cost base is dominated by bought-in goods, making it the largest available points pool. Building a supplier register linked to current certificates is usually the highest-return action available.
Can retailers use the Youth Employment Service?
Yes, and the fit is unusually good. The mechanism recognises measured entities meeting defined youth employment targets with a level improvement, and this industry already employs young people at scale. The enabling gazette and practice note are published by the regulator.
Map the entities, then map the spend
A structure and procurement review establishes how many measured entities your group actually has, which band each falls into, and how much of your existing supplier spend can be claimed once certificates are collected. You get the register as a working document, not a slide.
No obligation. We will get back to you within 24 hours.
Request a structure and procurement review
Dr. Este Welman, CA(SA)
Founding Director, Insignis Solutions
Dr. Welman is a Chartered Accountant holding a PhD in Economic Transformation from the Da Vinci Institute, an M.Comm in Tax from North-West University, and a B-BBEE Management Diploma from Wits. She is a member of SAICA. Working with multi-entity groups has taught her that the first question is rarely about the scorecard: it is how many separate businesses are actually being measured, and whether anyone has confirmed that in writing.