
CSI vs B-BBEE SED is the confusion that quietly costs companies scorecard points every year. The two look identical from the outside — both involve a company giving money to good causes — but only one earns recognition on the B-BBEE scorecard, and the rules that separate them are precise.
Corporate social investment is a voluntary philanthropy concept with no legal definition and no rulebook. Socio-economic development is a measured element of the B-BBEE scorecard elements, governed by Statement 500 of the Codes of Good Practice, with a target, a beneficiary rule and an evidence standard. Spend that qualifies as one does not automatically qualify as the other.
The practical loss is real. Companies give generously, book it as social investment, and discover at verification that most of it earns nothing because it never met the development rules.
Quick Answer
CSI vs B-BBEE SED comes down to rules. Corporate social investment is voluntary corporate giving with no legal definition — a company can support any cause it likes. Socio-economic development is a scorecard element under Statement 500 of the Codes of Good Practice, worth five points for spending 1% of net profit after tax, where at least 75% of the beneficiaries must be black. All qualifying development spend is social investment, but not all social investment qualifies as development. The difference decides whether your generosity earns points.
Giving generously but unsure how much of it scores? Send us your social spend and we will tell you what qualifies →
What CSI vs B-BBEE SED Actually Means
Start with the older idea. Corporate social investment is a business term, not a legal one. It describes the money and effort a company voluntarily puts into social causes, and it predates the empowerment framework by decades. There is no statute defining it, no target, and no rule about who must benefit. A company can fund a wildlife reserve, a private school or a hospital wing and call all of it social investment.
The development element is the opposite in every structural respect. It is defined in law, in Statement 500 of the Codes, carries a fixed target, and specifies exactly who must benefit for the spend to count. It exists to earn scorecard points, and it only does so when its rules are met.
The relationship between the two is a nesting one, not an overlap. Every rand of qualifying development spend is also social investment. But a great deal of social investment is not development spend, because it fails one or more of the rules. Picturing the two as concentric circles, with development sitting wholly inside the broader social-investment circle, is the mental model that prevents the expensive mistake.
The nesting relationship in one line
All qualifying socio-economic development is corporate social investment. Not all corporate social investment is qualifying development. A company that treats the two as interchangeable will fund causes that feel worthy but score nothing, while assuming it has covered the element. The scorecard only rewards spend that sits inside the smaller, rule-bound circle.
The Rules That Separate Points from Generosity
Three requirements turn ordinary giving into scoring development spend, and all three have to be satisfied at once.
The beneficiary rule. At least 75% of the value of the contribution must directly benefit black people, as defined in the Codes. Fund a cause whose beneficiaries are mostly not black, and the recognised value drops proportionally or disappears. This single rule disqualifies a large share of well-intentioned corporate giving.
The objective rule. The contribution must promote sustainable access to the economy for the beneficiaries — income-generating activity, skills, economic participation. A one-off donation with no developmental purpose does not qualify, even when the beneficiaries are entirely black.
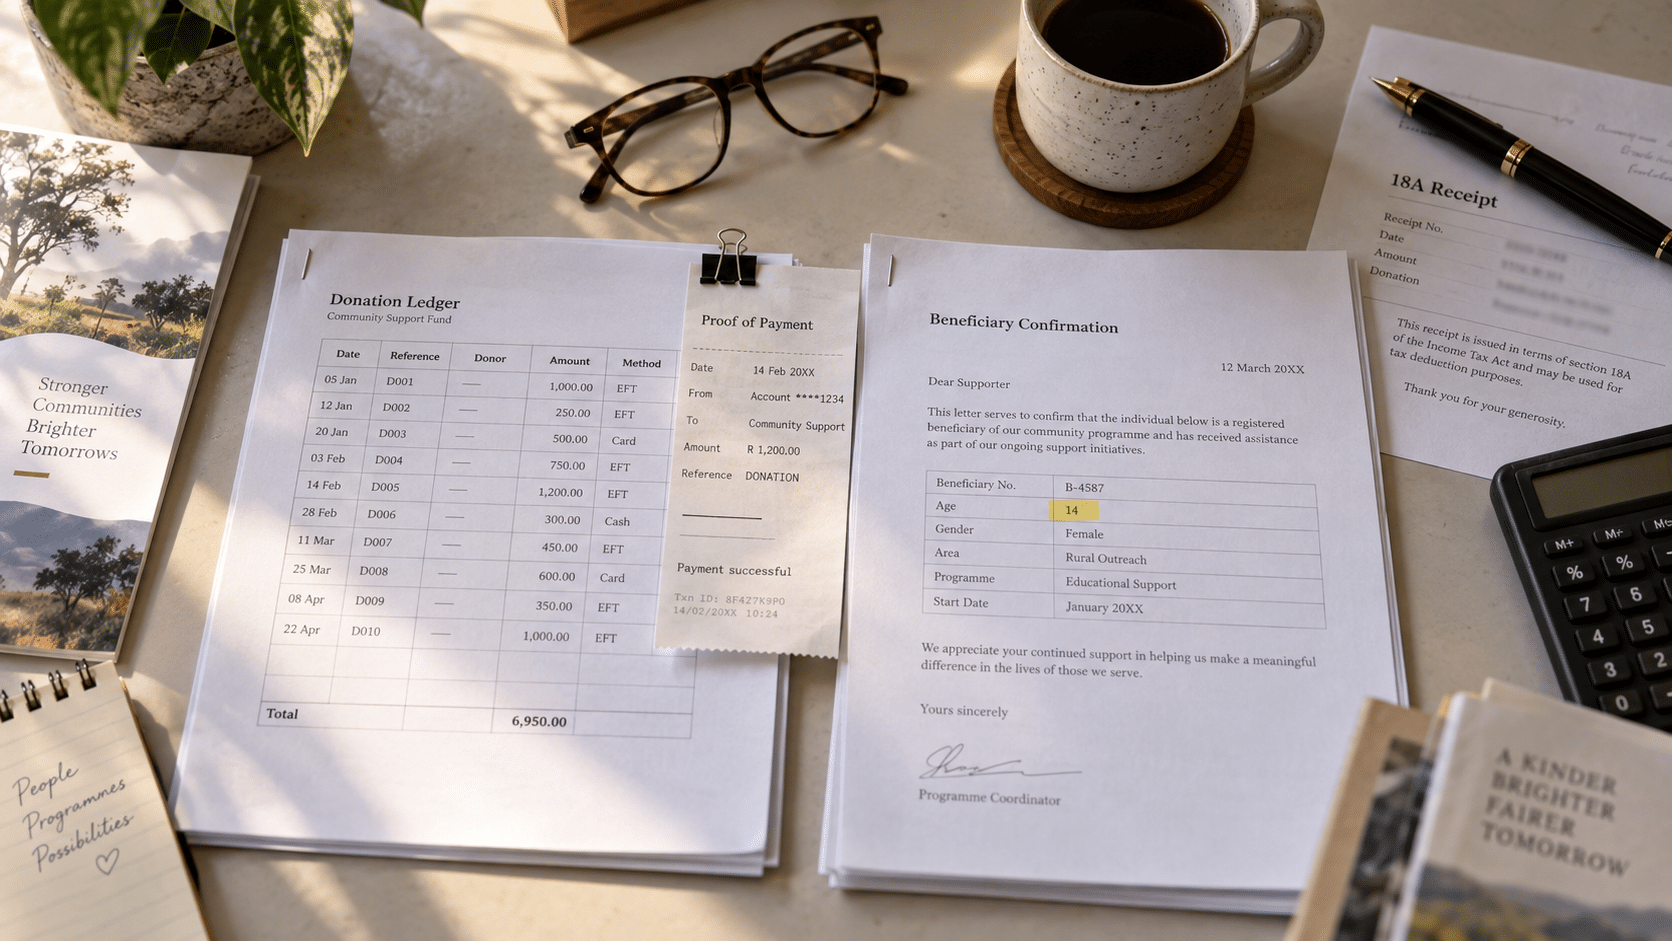
The evidence rule. The contribution must be quantifiable in money, proved by payment records, and accompanied by a beneficiary letter confirming the demographic and the allocation. Where the contribution is claimed as a tax-deductible donation, a Section 18A receipt supports it. Spend that cannot be evidenced this way cannot be claimed, however real it was.
Miss any one of the three and the spend falls out of the element and back into the wider, unrewarded pool of general social investment.
Not sure your beneficiary evidence meets the standard? Ask us to review your documentation before verification →
A Side-by-Side on What Actually Differs
Set against each other on the points that decide whether spend scores, the two diverge on almost everything that matters.
| Feature | Corporate social investment | Socio-economic development (scorecard) |
|---|---|---|
| Legal status | Voluntary, no legal definition | Defined in Statement 500 of the Codes |
| Target | None | 1% of net profit after tax |
| Scorecard points | None directly | 5 points on the generic scorecard |
| Beneficiary rule | Any cause | At least 75% black beneficiaries |
| Objective | Any social good | Sustainable economic access |
| Evidence | Optional | Payment proof + beneficiary letter mandatory |
That divergence is where the money leaks. A company can be an exemplary corporate citizen under the voluntary definition and score close to zero under the scorecard one, simply because its giving was never structured against the rules.
Why the Confusion Costs Real Money
The error is not abstract. It shows up as points that were available and never claimed, and it recurs for predictable reasons.
Legacy giving never gets re-pointed. Many companies have supported the same causes for years, chosen on genuine conviction rather than scorecard fit. That giving continues, the money leaves the business, and none of it is tested against the beneficiary and objective rules. It is generosity the scorecard cannot see.
The 75% rule is misjudged. A cause that feels broadly beneficial may not clear the demographic threshold on measurement. Companies assume a project qualifies because it is worthy, then find the recognised value cut because the beneficiary mix falls short.
Evidence is gathered too late. The beneficiary letter and payment records have to exist and match. Reconstructed after year-end, they are often incomplete, and an agency discounts what it cannot verify.
Non-monetary contributions go unvalued. Staff time, mentoring, and donated goods can all count, quantified properly. Treated as informal goodwill, they are simply never converted into claimable value.
The five points are usually already being spent
Most companies large enough to be measured already give more than 1% of net profit after tax to social causes. The problem is almost never the amount. It is that the spend was directed and evidenced as philanthropy rather than as socio-economic development, so it sits outside the element. Redirecting even part of an existing budget to qualifying beneficiaries, with proper evidence, frequently captures the full five points at no extra cost.
How to Make Giving Count Without Spending More
The fix is a structuring exercise, not a budget increase, and it runs in a clear order.
Audit the existing spend. List every social contribution the business already makes and test each against the three rules. This usually reveals that some spend qualifies untouched, some qualifies with minor changes, and some will never qualify.
Redirect at the margin. Where a contribution narrowly fails the beneficiary rule, a modest change in project or beneficiary selection can bring it inside the element without abandoning the cause. This is where most of the recoverable value sits.
Build the evidence trail in advance. Set up the beneficiary letters, payment records and demographic confirmations at the point of giving, not at year-end. Evidence gathered contemporaneously survives verification; evidence reconstructed under deadline does not.
Value the non-monetary. Quantify staff time, mentoring and in-kind contributions properly so they can be claimed. Understanding how the five scorecard elements work together helps here, because development spend can sometimes feed skills development too.
The Tax Overlap Most Companies Handle Badly
There is a second layer where the two ideas meet, and it is where a chartered accountant sees value that a transformation adviser often misses.
Many qualifying contributions can also be tax-deductible donations under Section 18A, provided the recipient is an approved public benefit organisation and issues the correct receipt. That means a single, well-structured contribution can do three jobs at once: support a cause, earn scorecard points, and reduce the company’s tax bill.
Most companies capture at most two of the three, and frequently only one. The giving happens, but the Section 18A receipt is never obtained, so the tax deduction is lost. Or the deduction is claimed, but the beneficiary letter needed for the scorecard is missing, so the points are lost. The three requirements are close cousins, and gathering them together at the point of giving is far easier than reconstructing any of them later.
The catch is that the rules do not perfectly align. A contribution can be tax-deductible without meeting the 75% black-beneficiary threshold, and it can meet that threshold without being tax-deductible. The overlap has to be engineered deliberately, contribution by contribution, rather than assumed.
Why net profit after tax makes timing matter
The 1% target is measured against net profit after tax, averaged over three years. That has a consequence companies rarely plan for: a strong profit year raises the rand target for the following measurement, and a business that fixed its giving budget in a leaner year can find itself quietly under target without having changed anything.
Modelling the target against a profit forecast, rather than last year’s outcome, keeps the contribution aligned with the moving benchmark. It is the same discipline that applies to any element measured as a percentage of a financial figure that moves each year.
What Changes When Giving Is Structured Properly
The figures below come from a composite of mid-sized corporate mandates across Gauteng and the Western Cape.
| Position | Before structuring | After structuring |
|---|---|---|
| Annual social spend | R1.8 million, philanthropy-directed | R1.8 million, unchanged |
| Spend qualifying as development | R400 000 | R1.6 million |
| Element points earned | 1.1 of 5 | 5 of 5 |
| Beneficiary evidence | Reconstructed at year-end | Captured at point of giving |
| Non-monetary value claimed | Zero | R240 000 in staff time and goods |
| Recognition-level effect | Element dragging the scorecard | Full element contribution |
The spend line is deliberately identical. The business gave exactly the same amount before and after. Everything that changed happened in how the giving was directed and evidenced, not in how much left the account.
Who This Is NOT For
Exempt micro enterprises on an affidavit. Below the exemption threshold, the element is not separately scored in the way it is for larger entities. If you qualify for the affidavit route, structuring your giving for points adds little.
Companies giving purely for conviction, indifferent to points. If a business supports a cause because it believes in it and does not care whether it scores, that is a legitimate choice. This exercise is for those who want the giving to do both jobs.
Anyone hoping to relabel old donations without changing anything. Spend that fails the beneficiary or objective rule cannot be claimed by calling it development. The rules are tested on substance, and misrepresenting a contribution is an offence under the Act.
Businesses wanting a number before a verification next week. Proper beneficiary evidence takes time to assemble correctly. If the deadline is days away, work with what is already documented rather than starting fresh.
Who this does suit: measured entities already giving at or above 1% of net profit after tax, companies whose social spend has never been tested against the development rules, and any business whose element score sits well below five points despite a healthy giving budget.
How Insignis Turns Giving Into Recognised Development
We start by separating the two questions most companies have merged. What do you want to support, and what earns recognition? Those are not the same question, and the value lies in the overlap between them rather than in choosing one over the other.
The audit is the core of the work. We take the existing social budget, test every line against the beneficiary, objective and evidence rules, and show precisely which spend qualifies, which can be brought inside the element with a small change, and which will never count. Almost always, the recoverable points are already being funded.
Because the element is calculated on net profit after tax and interacts with the tax treatment of donations, this is an accounting question as much as a transformation one. A chartered accountant with a tax specialisation reads the 1% target and the Section 18A angle together rather than separately. Our socio-economic development advisory covers the full exercise from our Centurion base.
The regulator publishes its own guidance on how the element is defined and measured, which is the authoritative reference when a beneficiary or evidence question is genuinely borderline. The B-BBEE Commission’s educational material on socio-economic development sets out the Statement 500 requirements in full.
Social budget healthy but element score low? Book an audit of what already qualifies →
Frequently Asked Questions
What is the difference between CSI and SED?
Corporate social investment is voluntary corporate giving with no legal definition or rules. Socio-economic development is a measured B-BBEE scorecard element under Statement 500, worth five points for spending 1% of net profit after tax, where at least 75% of beneficiaries must be black. All qualifying development spend is social investment, but not all social investment qualifies as development.
How much must a company spend on the development element?
The target is 1% of net profit after tax for the full five points, calculated on the average of the three preceding years of audited financials. Points are awarded proportionally, so spending less than 1% earns a proportional share of the five points rather than nothing.
Who must benefit for spend to qualify?
At least 75% of the value of the contribution must directly benefit black people as defined in the Codes. If the demographic threshold is met, the full value is recognised; if it is lower, only the proportion benefiting black people counts.
Can corporate social investment count towards the scorecard?
Only the portion that also meets the development rules. Social investment directed at causes that fail the 75% beneficiary rule or the sustainable-economic-access objective earns no scorecard points, however valuable the cause.
What evidence is needed to claim the points?
Proof of payment and a beneficiary letter confirming that at least 75% of beneficiaries are black and that the full contribution was allocated to them. Where the contribution is a tax-deductible donation, a Section 18A receipt supports the claim.
Can non-monetary contributions count?
Yes. Staff time, mentoring and donated goods can be recognised when quantified in monetary terms and evidenced. Many companies overlook this and claim only cash donations, leaving recognisable value unclaimed.
Turn the giving you already do into scorecard points
An audit tests every line of your existing social budget against the development rules, shows exactly what qualifies as it stands, what a small change would bring inside the element, and how to evidence it so it survives verification. You capture the points without increasing the budget.
No obligation. We will get back to you within 24 hours.
Request a giving-and-scorecard audit
Dr. Este Welman, CA(SA)
Founding Partner, Insignis Solutions
Dr. Welman is a Chartered Accountant holding a PhD in Economic Transformation from the Da Vinci Institute, an M.Comm in Tax from North-West University, and a B-BBEE Management Diploma from Wits. Because the element runs off net profit after tax and touches the tax treatment of donations, she tends to see the giving budget and the scorecard as one problem, where many advisers treat them as two conversations that never meet.